Two numbers from the same market, in the same year.
Zudio added 198 stores in FY26.
Zara India’s profit fell 32 per cent.
Almost everything worth knowing about Indian fashion right now sits in the space between those two facts.
The 59 per cent nobody counts
Before any comparison of brands is useful, one figure has to be on the table: about 59 per cent of India’s fashion market is unorganised.
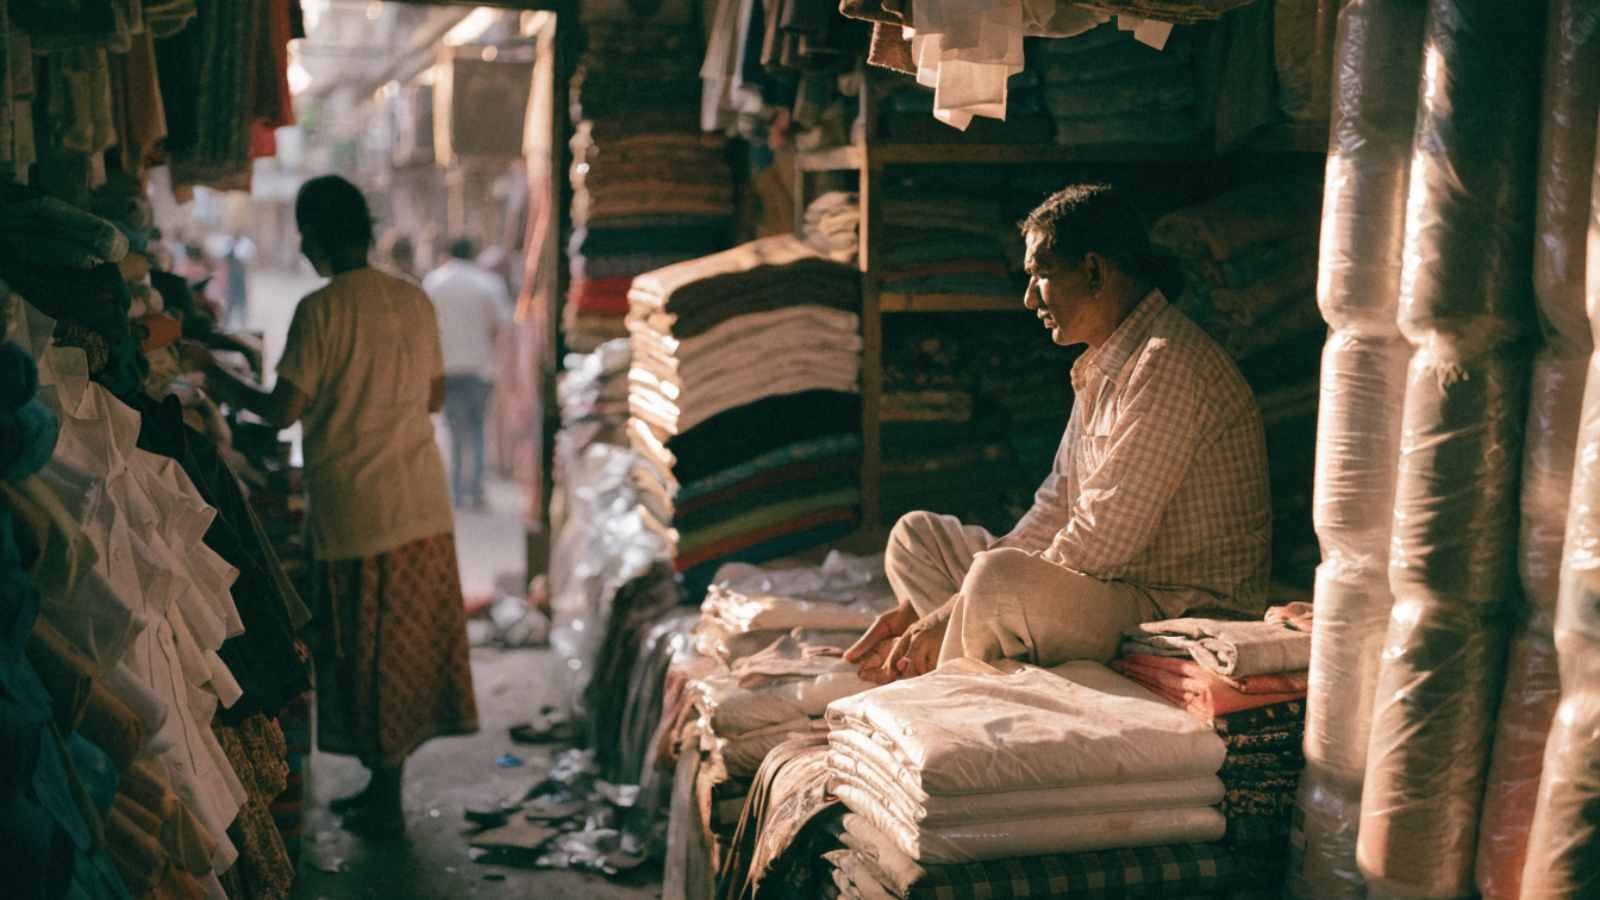
That is the local cloth shop, the tailor, the weekly market, the wholesale hub — businesses that file no retail data, appear in no market-share table, and are absent from every strategy deck written about Indian fashion.
So when a consultancy reports that a brand holds a certain share of the market, it means a share of the 41 per cent that is measured. The largest player in Indian fashion is not a company. It is the category of businesses that were never counted.
This matters for the rest of this article, because the competitive threat to a ₹999 branded t-shirt is not another brand. It is a ₹250 unbranded one from a shop that has served the same street for thirty years.
What value retail figured out
Zudio’s expansion rate is not a marketing achievement. It is a supply-chain one.
The model works because the price point is set first and everything else — fabric selection, order quantity, store size, location, staffing — is engineered backwards from it. Stores are deliberately unglamorous. Inventory turns fast enough that markdowns are rare. Sourcing is kept close to home wherever possible.
Global fast fashion in India runs the opposite way: a global assortment, a global price architecture, and Indian stores in expensive mall real estate that were sized for a customer base that grew more slowly than anyone projected.
Zara India is not failing. It is a profitable business having a bad year in a market that has moved downmarket faster than its format allows it to follow.
The export side is going the other way
Domestic value retail is expanding. Indian textile and garment exports fell 2.2 per cent in 2025-26, to about $35.8 billion.
A big part of the cause is the US tariff regime. From 27 August 2025, Indian textiles faced a 50 per cent tariff in their single largest market. The extra 25 per cent penalty was lifted from 7 February 2026, the 18 per cent rate announced under the interim trade deal was never actually applied, and after the US Supreme Court struck down those tariffs on 20 February, a temporary 10 per cent global duty took their place.
More than five months of punitive pricing was long enough to do structural damage. American buyers do not switch sourcing back quickly once they have qualified a supplier in Vietnam or Bangladesh; the re-qualification cost is real and the relationship inertia is stronger than the tariff differential.
Lower rates improve the arithmetic considerably. They do not automatically return the orders.
Two industries wearing one name
It is worth being clear that India’s fashion sector is really two businesses that share a word.
One is domestic retail — growing, increasingly value-led, largely insulated from global trade policy, and competing mostly against the unorganised trade.
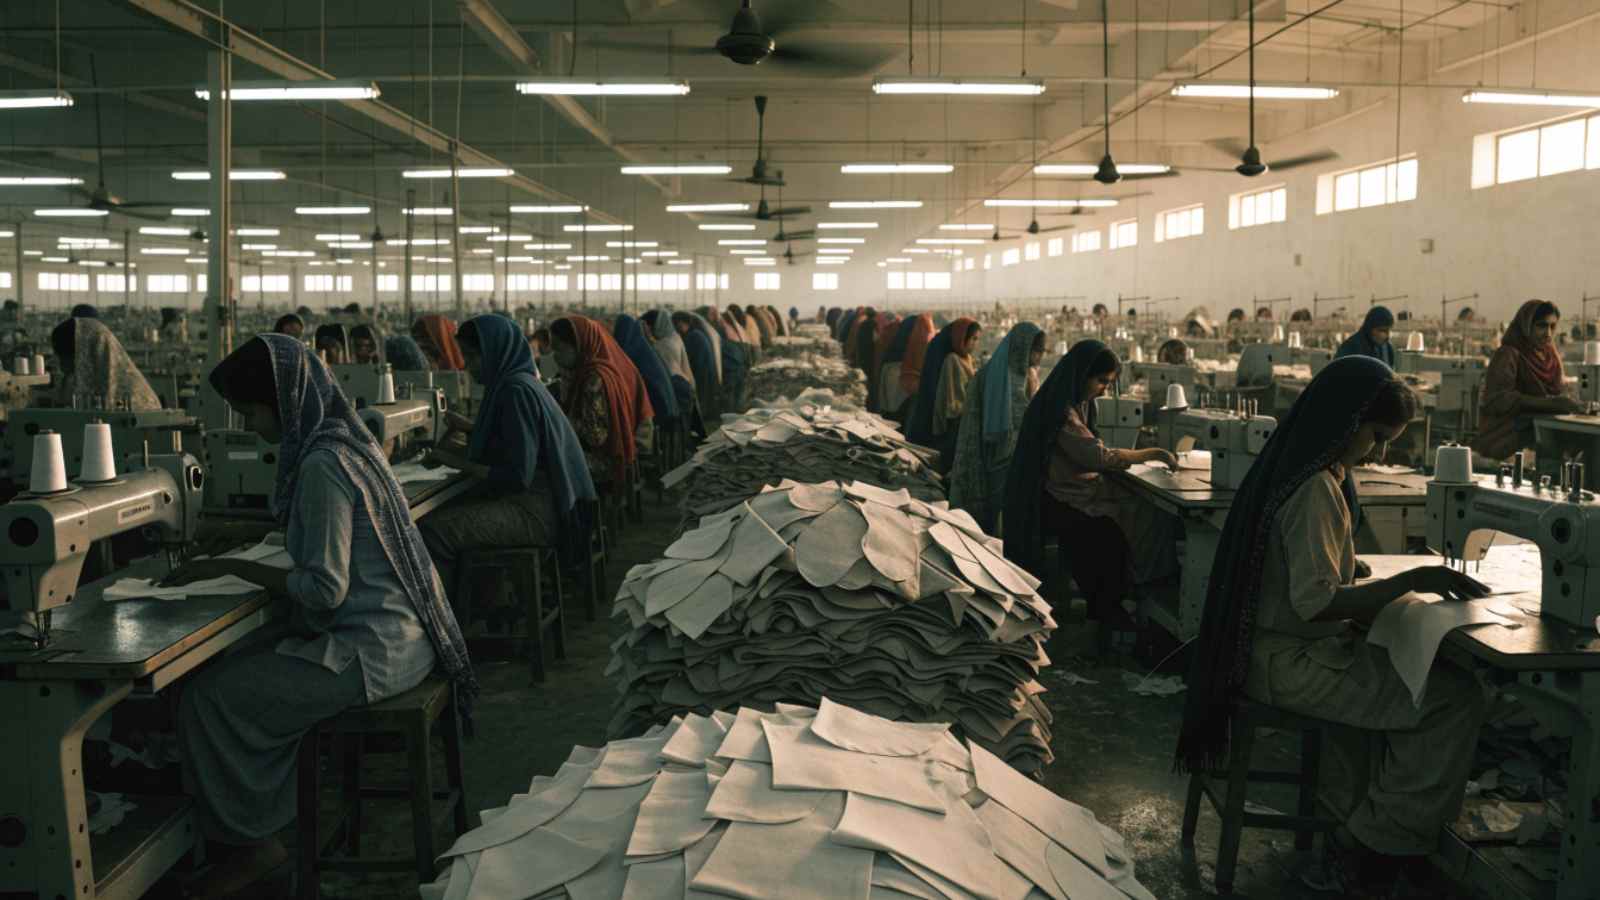
The other is export manufacturing — employment-heavy, concentrated in Tiruppur, Surat, Noida and Bengaluru, and entirely exposed to decisions taken in Washington and Brussels.
Policy tends to address them as one industry. They have opposite problems. Domestic retail needs consumption to hold up. Export manufacturing needs market access, and no amount of Indian consumer demand substitutes for it.
7.8 million tonnes
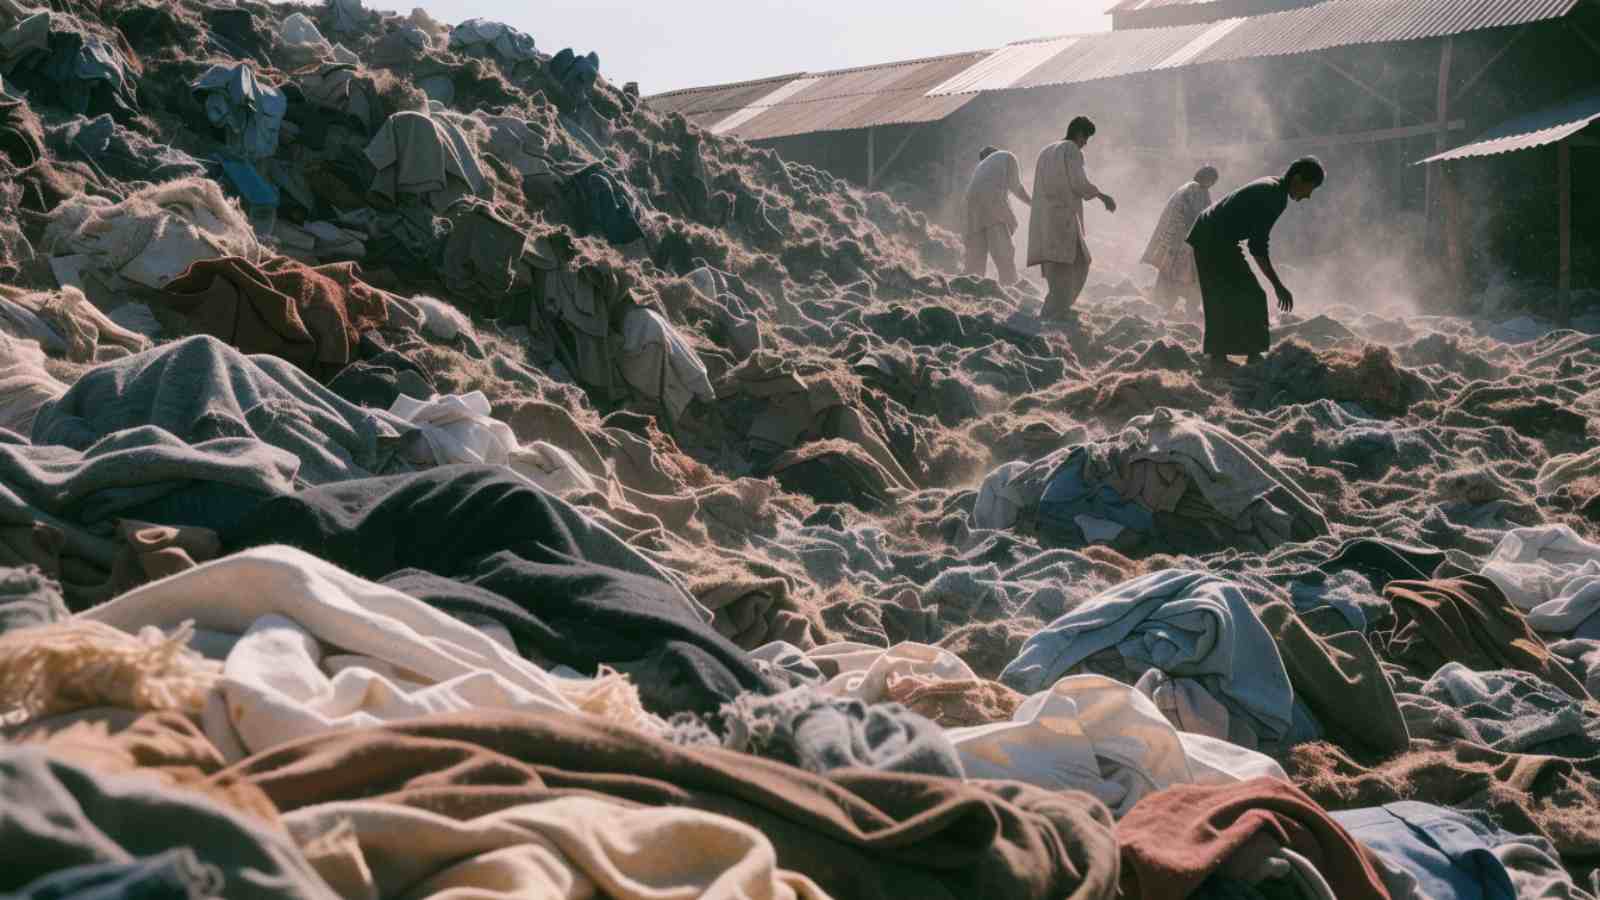
India generates roughly 7.8 million tonnes of textile waste a year, about 8.5 per cent of the global total, according to a Fashion for Good study.
Some of it is post-consumer. A great deal of it is industrial — cutting-room waste, rejected lots, overproduction from an order that was cancelled downstream.
Panipat has recycled textiles at scale for decades, largely informally, and handles a meaningful share of the world’s shoddy yarn. It is one of the few genuine circular-economy systems anywhere in global fashion, and it operates almost entirely outside the sustainability discourse that brands fund.
The uncomfortable arithmetic: the business model driving domestic growth — fast turns, low prices, high volume — is a waste-generation model. Expanding it and reducing textile waste are not compatible goals, and no Indian retailer has yet had to answer for that.
What this means if you are buying clothes
Three practical consequences of the shift, none of them marketing claims.
Quality variance at the value end is high and unlabelled. Two ₹499 t-shirts from different value chains can differ substantially in GSM and construction. Fabric weight is the single most useful thing to check and is almost never printed.
The unorganised trade is frequently better value than either. A local shop buying from the same mills, without the brand margin or the mall rent, routinely undercuts organised retail on comparable cloth. It just cannot advertise.
Discounting at the premium end is now structural. When international brands see profit compression in a market they cannot exit, sale periods lengthen. Waiting is a viable strategy in a way it was not five years ago.
Where this goes
The likely shape of the next few years: value retail keeps taking share from the unorganised trade rather than from international brands, international brands hold their premium positioning and shrink their footprint, and the export side recovers partially but not to its pre-tariff baseline.
The part that remains genuinely open is whether anyone builds a credible Indian brand in the middle — above value, below international, with actual design identity. That segment has been declared imminent for a decade and has produced very few survivors.
India can now make clothes cheaply at enormous scale and sell them through modern retail. What it has not yet built is a reason for anyone to pay more than the minimum.
Store-count and financial figures are drawn from company filings for FY26. Export data is for 2025-26 against 2024-25, as compiled by GTRI. Unorganised-market share is a CareEdge Ratings estimate and, by the nature of the segment, cannot be precisely measured.