Indians made 25.47 billion UPI payments worth ₹31.53 lakh crore in October, and for the first time the average day crossed ₹1 lakh crore. The record arrives just before UPI’s zero-fee era ends for a slice of merchant payments. Here is what the numbers show, and what the new charge does and does not touch.
A record month, by every measure
NPCI data for October 2026, reported by Business Standard on 1 November, shows UPI processed 25.47 billion transactions worth ₹31.53 lakh crore. That is 23 per cent more transactions and 16 per cent more value than October 2025, when the network handled 20.7 billion payments worth ₹27.27 lakh crore.
The daily figures are the headline. UPI averaged 822 million transactions a day, its highest ever, and the average daily value went past ₹1 lakh crore for the first time. Entrackr, working from the same NPCI data, put the daily average at ₹1,01,707 crore, up from ₹97,913 crore in September.
Month on month, volume rose from 24.06 billion in September and value from ₹29.37 lakh crore. Part of that jump is calendar: October has 31 days to September’s 30. Even so, the per-day numbers rose too.
Bigger baskets, but not bigger than last year
“The festive season drove this rise,” Reeju Datta, co-founder of Cashfree, told Business Standard. He pointed to Navratri and the big online sales falling in October, with people using UPI for larger festive purchases alongside their everyday payments. Between April and August, he said, the number of payments kept rising while their daily value stayed flat, so the average payment shrank; in September and October, value grew faster than volume.
Dividing the reported totals shows how modest that shift is. The average UPI payment worked out to about ₹1,217 in August, ₹1,221 in September and ₹1,238 in October. A year earlier, in October 2025, it was about ₹1,317.
So the festive bump is real, but the longer trend still points the other way. Volume is growing faster than value year on year, which means UPI keeps spreading into smaller, everyday payments: the chai, the auto fare, the kirana bill. That matters for the fee that comes next, because the fee is aimed only at the bigger payments.
The charge that was due on 15 October
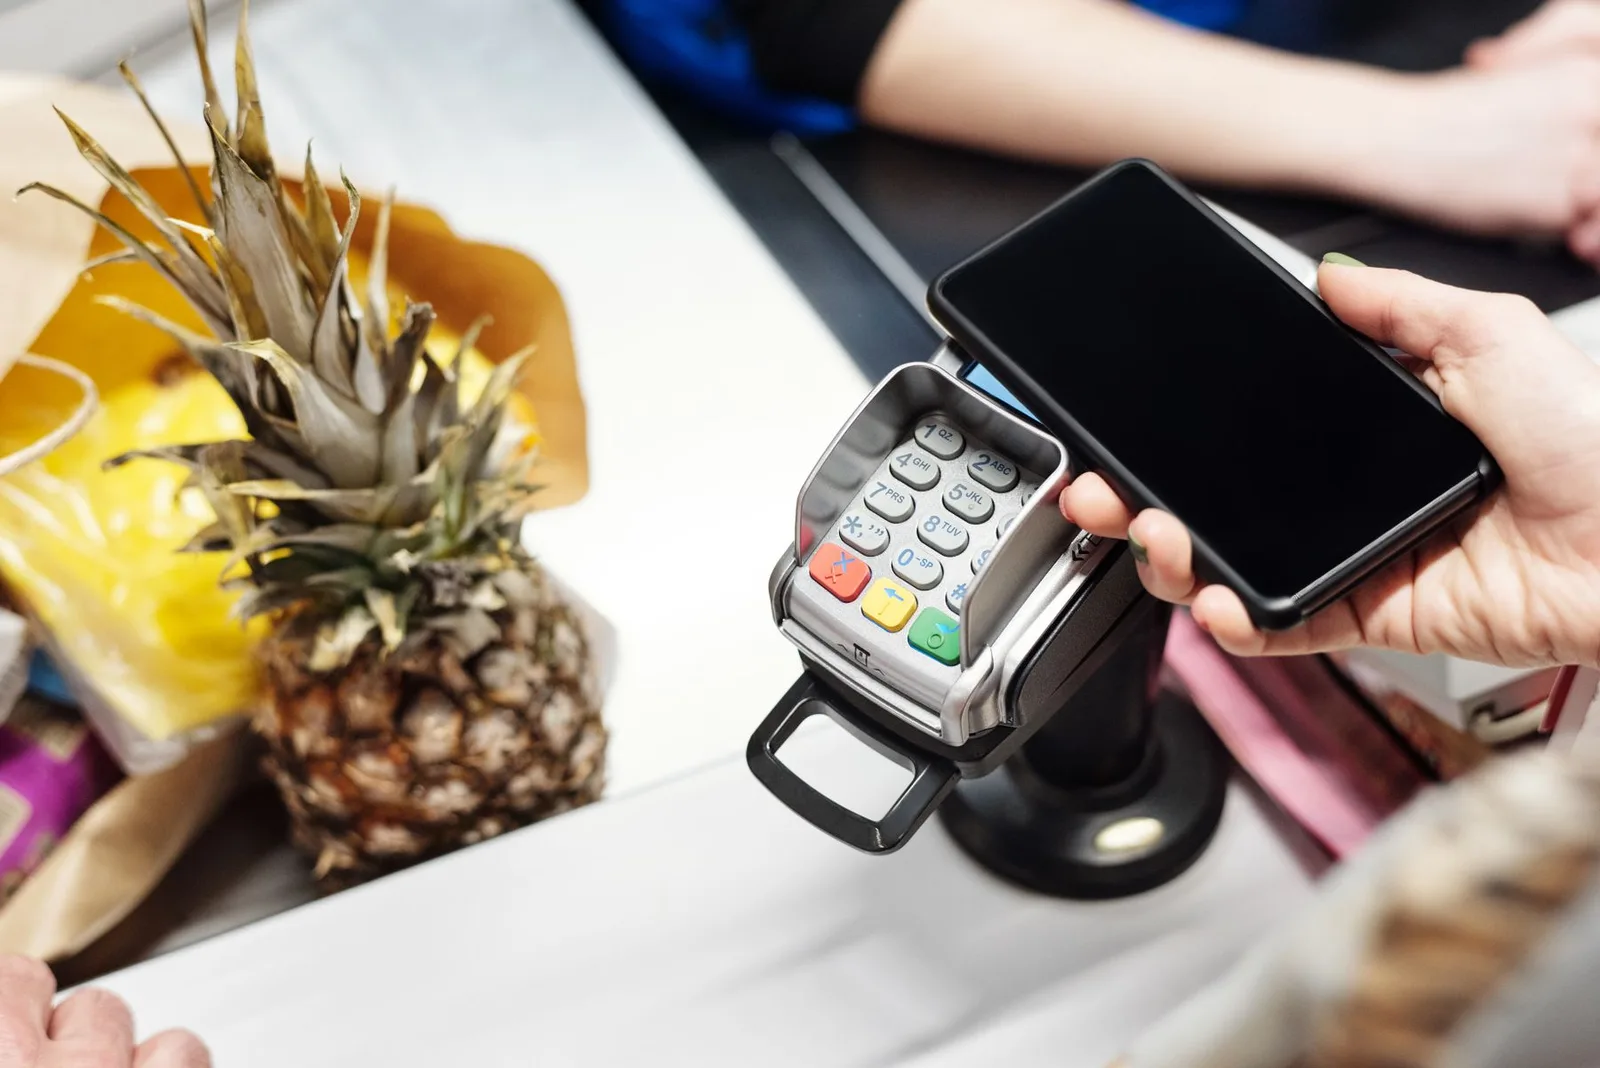
On 15 September, an FAQ published on the Finance Ministry’s Department of Financial Services website set out a merchant discount rate (MDR) for UPI. MDR is the fee a shop pays its bank to accept a digital payment. Under the framework, person-to-merchant UPI payments above ₹2,000 attract 0.4 per cent, capped at ₹300 for payments of ₹75,000 and above. It was due to start on 15 October.
On 13 October, the UPI and Services Steering Committee deferred it. NPCI said the charge “shall be implemented immediately post Diwali, on a date to be notified separately”, citing the festive period, The Tribune reported. That same report said the fee is now expected from January, though that is the paper’s expectation, not an official date.
Who pays, and who does not
The merchant pays, not the customer. The FAQ says consumers will not face any charges, merchants cannot pass the MDR on, and UPI apps cannot add platform fees. Person-to-person transfers stay free, as do merchant payments of ₹2,000 or less. The government says payments at or below that line make up more than 95 per cent of person-to-merchant UPI volume.
The FAQ’s own examples: a ₹3,000 payment costs the shop ₹12, a ₹50,000 payment ₹200, and a ₹1 lakh payment hits the ₹300 cap. Some categories get different terms. Railways, telecom, insurance, fuel and utility bills pay a flat ₹5 per payment above ₹2,000. Mutual funds and stockbrokers pay 0.02 per cent, capped at ₹300. Recurring AutoPay mandates, including mutual fund SIPs, OTT subscriptions and utility bills, are exempt, and credit-linked UPI sits outside this framework.
Small sellers are protected by a collections test, not a turnover test. A merchant receiving up to ₹1 lakh a month through UPI QR codes pays nothing. Only if inward UPI credits cross ₹1 lakh for three months in a row does the bank move that merchant into the paying category.
Why the free ride is ending
UPI has run on zero MDR since 2020, a model banks and payment firms had called unsustainable, according to The Tribune. The FAQ cites industry estimates that running UPI costs around ₹20,000 crore a year, and says government subsidies are not a permanent source of funding. The new fee is to be shared only within the UPI ecosystem, for infrastructure, cybersecurity, fraud detection and customer service, with a separate fund for small-merchant onboarding.
The government’s case rests on comparison. Credit card MDRs typically run at 1.5 to 2.5 per cent per payment and debit card MDRs are capped at up to 0.90 per cent, so even at 0.4 per cent, UPI remains the cheapest digital option for a shop. The Finance Ministry has also stressed that MDR “is neither a tax nor a charge collected by the Government or NPCI”.
What to watch
First, the notification date. Until NPCI names one, every larger shop payment is still free to accept. Second, November’s numbers, when NPCI releases them, which will show whether the festive rise in average payment size holds once the sales end.
Third, enforcement at the counter. The rule says merchants cannot pass the fee on, but a shop that pays ₹40 on a ₹10,000 UPI payment may quietly prefer cash or ask for a split payment. Whether that happens, and whether the small-merchant fund framework arrives on time, will decide how smoothly UPI’s paid era begins.